
Self exclusion gaming apps – Complete 2026 Guide to Taking a Break
You have already uninstalled the app once, maybe twice, and reinstalled it inside a week — and closing that reinstall gap is exactly what self exclusion gaming apps tools are built to do. Deleting an icon removes a shortcut; it does not remove the account, the saved card, the push notifications, or the two-minute path back in. A break that holds is built in layers, so that no single moment of impulse can undo the whole thing.
Most of what is written about this online describes British high-street schemes and card blocks offered by UK banks, which tells someone using an app in India almost nothing useful. This breakdown sticks to what you can actually set up yourself today: inside the app, on your phone, and with your bank.
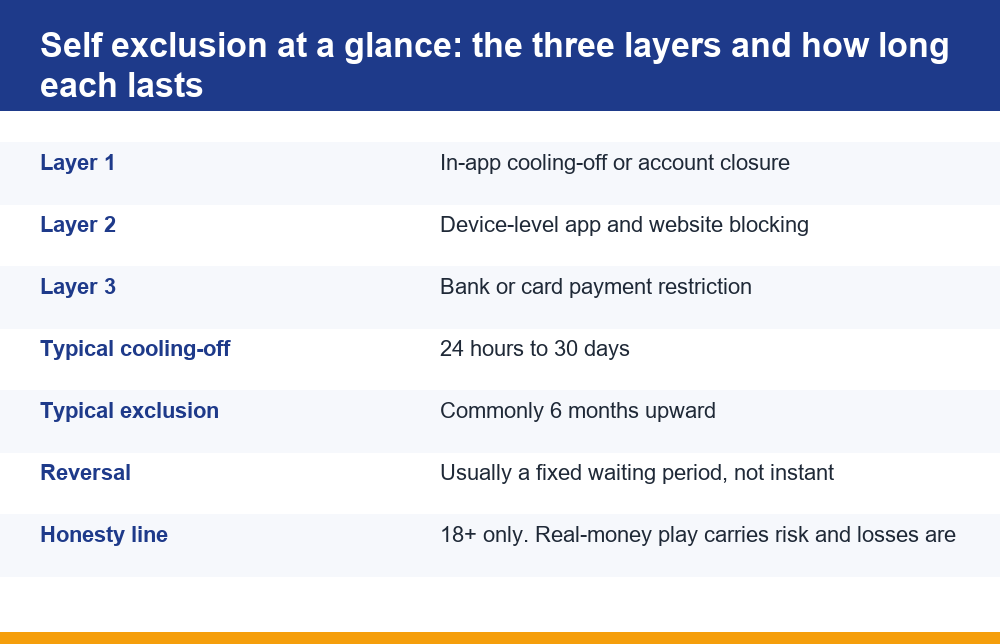
What self exclusion gaming apps actually means
Self exclusion is a voluntary instruction you give in advance that removes your own ability to act on a later impulse. You are not asking anyone’s permission and you are not being punished. You are making a decision once, while calm, and arranging things so that the version of you at 1 a.m. cannot quietly overturn it.
In the context of self exclusion gaming apps, the instruction can be given to three different parties, and this is the part most write-ups skip. You can give it to the platform itself, which closes or freezes the account. You can give it to your phone, which refuses to open or install the app. Or you can give it to your bank, which declines the transaction when a deposit is attempted. Each of these stops a different thing, and each one on its own has an obvious hole in it.
The word that matters is voluntary. Nothing here is imposed on you, nothing is recorded against your name anywhere public, and nobody has to be told. It is closer to putting a timer lock on a cupboard than to signing a document. The reason it works at all is friction: not because the barrier is unbreakable, but because breaking it takes long enough for the urge to lose its edge.
It is also worth separating a break from a limit. A limit keeps you playing with a ceiling on it, which suits someone who is comfortable with their own pattern and simply wants a boundary. A break removes playing from the picture for a defined stretch, which is a different request you are making of yourself and needs different machinery. Confusing the two is why people set a deposit cap, feel they have acted, and find themselves in the same place a month later having capped nothing that mattered.
It also helps to be honest about what self exclusion is not. It is not treatment, and it is not a substitute for talking to someone if the money or the hours have become a serious problem. It is a containment tool. It buys you weeks of not-playing, which is often what makes the rest of the work possible. If you have not yet mapped out why the pull is strongest at particular moments, reading about the cycle of cue, play and chase that keeps sessions going alongside setting up the block will make the break far more likely to hold.
The three layers of a break that holds
People usually try one layer, watch it fail, and conclude the whole idea does not work. In practice the layers are meant to overlap, so that each one covers the gap left by the others. Close an account and you can open another; block an app and the browser version still loads; block the browser and a friend’s phone still works. Restrict the money and suddenly none of those routes end anywhere.
| Layer | What it stops | Where it leaks | How fast to set up |
|---|---|---|---|
| In-app cooling-off or closure | Logging in and depositing on that specific account | Other apps, new accounts, re-registration after the period | Minutes, inside the app |
| Device-level blocking | Opening or reinstalling apps and sites on that phone or laptop | A second device, a borrowed phone, a work laptop | 10 to 20 minutes per device |
| Bank or card restriction | The payment itself, whichever app is used | Wallets already loaded, payment handles not covered, cash via a friend | A call or a branch visit; sometimes a day or two |
Read the leak column honestly rather than defensively. The point is not that a set of self exclusion gaming apps measures is escape-proof — it is not, and anyone who tells you otherwise is selling something. The point is that each layer adds minutes or days to the escape route, and an urge that has to survive a phone call and a two-day wait is a very different thing from one that only has to survive an unlock.
A reasonable order of operations is to start with the money, because it is the layer that works regardless of which app or site is involved, then do the device, then close the individual accounts. Doing it in that order means that even if you stall halfway through, the half you finished is the half that matters most.
Give yourself about an hour and do all three in one sitting. Spread across a week, the unfinished layers tend to stay unfinished, and a half-built setup is the version most likely to fail in a way that convinces you none of it works.
In-app cooling-off periods and account closure
Most real-money apps carry some version of a self-control menu, usually filed under account settings, responsible play, or limits. The naming is inconsistent and the menu is rarely where you would expect it, which is itself worth noticing. Typically you will find three distinct things grouped together, and they are not interchangeable.
- Deposit or spend limits — you keep playing but cap what can go in. Useful as a step down, not as a break.
- Cooling-off or time-out — the account is frozen for a short fixed window, commonly 24 hours, 7 days, or 30 days. Balance usually stays where it is and the account reopens automatically when the window ends.
- Self exclusion or permanent closure — a longer block, often six months upward, which does not auto-reopen and usually cannot be lifted on request during the period.
A cooling-off period is best understood as a circuit breaker rather than a decision. It exists for the moment when you know you should stop for today but do not trust yourself to. Because it ends by itself, it asks nothing of your future willpower — which is also its weakness, since the account quietly comes back to life without you choosing it.
Before you trigger anything, withdraw the balance. People skip this and then spend the exclusion period with money parked in an account they cannot reach, which turns the break into a countdown to a payday. Also take the saved card or payment method off the account first, because it often survives closure and reappears the moment you re-register. If limits are the step you want before a full break, the mechanics of setting a loss cap you cannot quietly raise mid-session are worth getting right first.
Expect the wording to be vague and the confirmation to be thinner than you would like. Some apps apply the freeze immediately, some apply it at the end of the day, and some ask you to confirm by email before anything happens, which means the block is not in place until you have clicked that link. Check that you are actually logged out and cannot log back in before you consider the step done.
Keep a record. Screenshot the confirmation, note the date, and save any reference number or email. Support conversations about an exclusion go very differently when you can produce the confirmation yourself.
How to block gaming apps on your own phone, step by step
Device-level blocking is the layer you control completely, needs nobody’s cooperation, and takes about fifteen minutes. The aim is not only to stop the installed app from opening but to stop a new one being installed and to stop the browser version loading, because that is the route almost everyone forgets.
- Uninstall the apps first, so there is nothing to tap by reflex.
- Open your phone’s built-in digital wellbeing or screen time controls and set a restriction on the app category, then set a passcode you do not use anywhere else.
- Turn on app-install restrictions in the same settings area, so a reinstall needs that passcode rather than a fingerprint.
- Add a content or website restriction in the browser settings for the same category, and repeat it for every browser on the phone, not just the default one.
- Remove saved cards, saved payment handles and autofill entries from the browser and from the phone’s payment wallet.
- Turn off and clear notifications and marketing emails, then unsubscribe properly — a push notification is a very common restart trigger.
- Hand the passcode to someone you trust, sealed in a note or simply typed into their phone, so that unlocking it requires a conversation.
That last step is the one that does the real work, and the one people resist hardest. A block you can lift alone is a speed bump. A block that requires you to ring your brother and explain why you want the code is a genuine barrier, because the explanation is harder than the urge.
Dedicated blocking tools also exist alongside built-in settings, and some are designed so that they cannot easily be removed while a block period is still running, which is the one thing phone settings alone do not give you. Britain’s gambling-harm charity GambleAware sets out the same layered thinking in its overview of gambling blocking and self-exclusion, which is a reasonable reference point for how the pieces fit together, even though the UK-specific schemes it names do not cover apps used in India.
One practical warning: do not build the block around deleting your account on the phone and nothing else. Browsers remember logins for a long time, and a saved session can put you back inside a web version without a password at all. Clear browser data for the relevant sites, remove any saved passwords for them, and then set the restriction, in that order.
Finally, repeat the whole process on every device that can reach a browser: the second phone, the tablet, the work laptop, the smart TV. An unblocked device is not a loophole you will notice in advance — it is one you will discover at the exact moment you are looking for it.
Asking your bank to restrict payments
This is the layer that almost nothing written for app users in India explains, and it is the strongest of the three because it is indifferent to which app you use. If the deposit cannot clear, the app is irrelevant.
What you are asking for varies by bank, and you may need to ask more than once before reaching someone who knows the options. Broadly, the things worth asking about are a merchant-category restriction on your debit or credit card, lowering your daily online transaction limit to a nominal figure, disabling online or international use on the card entirely, capping your per-transaction and daily payment limits, and switching off card-on-file or recurring payment mandates. Not every bank offers every option, and some are available in the banking app under card controls without needing to speak to anyone at all.
- Check your own banking app first, under card controls or transaction limits — a surprising amount can be switched off there in under a minute.
- If you call, ask specifically for a merchant restriction rather than describing the problem, since front-line staff recognise the request more readily than the reason.
- Ask what the reversal process is before you set it, so you know whether the restriction has teeth.
- Remove the gaming apps from any wallet or autopay list separately — a card block does not always cover a wallet that is already funded.
- Note that a payment restriction of this kind is a service setting on your own account, and it does not affect your ability to spend elsewhere.
- Write down what you changed and when, because card controls are easy to flip back without quite deciding to.
If you hold more than one card or more than one account, the exercise is only finished when all of them are covered. A single unrestricted card in a drawer does the same job as an unblocked tablet: it waits quietly until the one evening you go looking for it. The same applies to any credit line, overdraft facility or buy-now-pay-later arrangement attached to the account, since those are the routes that turn a bad evening into a debt rather than a loss.
One honest caveat: money is slippery. A card block does not stop a loaded wallet, a second account, a borrowed phone, or someone else paying on your behalf. Treat the bank layer as the wall that handles the ordinary, impulsive, half-asleep attempt — which is most of them — not as a vault. The broader habits that sit around this, and the self-checks worth running monthly, are covered in the overview of practical safeguards for real-money play in India.
Does self exclusion actually work?
The honest answer is more useful than the confident one: the direction of the evidence is positive, and the size of the effect is uncertain. Research into voluntary limit-setting and exclusion tools has generally found that people who use them deposit and spend less afterwards than they did before, and less than comparable users who set nothing. That pattern has shown up across different markets and different tool designs, which is why these features exist at all.
Be sceptical of round numbers, though. Published figures vary widely depending on how spend was measured, over what window, and critically on whether the study could see activity that moved elsewhere. A reduction measured on one platform is not the same as a reduction in total spend, because some of it simply relocates. Anyone quoting you a single tidy percentage is reporting one study as if it were a law, and you should ask which study and over what period before you believe it.
Three things look sturdier than any specific number. First, longer exclusion periods tend to hold better than short ones, because short breaks end before habits have had time to change. Second, tools used in combination appear to outperform any single tool, which is the whole argument for the three-layer approach. Third, the technical block is not the only ingredient — people who also tell someone else tend to do better, which suggests self exclusion gaming apps measures work partly as a social commitment and not only as a switch.
The flip side is documented too: some people who exclude on one platform turn up on another before long. That is not a reason to skip it. It is a reason to do all three layers at once rather than testing one and calling the experiment finished.
It also helps to define what working means before you start. If the measure is never feeling the pull again, nothing will pass. If the measure is how many evenings in the next six months you did not play, and how much of your month stayed in your account, then a layered setup is a tool with a decent record rather than a promise.
Reversing a self exclusion if you change your mind
It depends which layer you are talking about, and the differences are deliberate rather than accidental. Each layer is built with a different amount of friction on the way out, and knowing which is which before you start tells you how much your future self will be able to undo in a hurry.
A cooling-off or time-out generally cannot be cut short. It runs its fixed window and then lapses on its own, which means you do not reverse it so much as wait it out. A longer self exclusion usually cannot be lifted at all during the stated period; at the end of it, reopening typically requires an explicit request and often a waiting period on top, precisely so that the decision to come back cannot be made inside a single urge.
Device-level blocks can be removed by whoever holds the passcode, which is the argument for that not being you. Bank restrictions can normally be reversed by asking, though some banks apply a deliberate delay before the block comes off, and some require the same channel you used to set it. That is the layer most worth asking about in advance, because a restriction you can flip in the banking app in four taps is weaker than it feels when you set it.
If you find yourself trying to reverse something within days of setting it, that is worth treating as information rather than an obstacle. The urge to undo a break is the same urge the break was built to interrupt, and it being inconvenient is the feature working as intended. Waiting out the delay costs you nothing you will miss.
Where it genuinely does matter — a pending withdrawal, a verification issue, money you need to reach — contact support about the specific transaction rather than asking for the exclusion itself to be lifted. The two requests are separable, and conflating them often gets both refused. Put the account reference and the date in the first message, and keep the thread about the money rather than about the block.
Mistakes that quietly break a self exclusion setup
Most failed attempts at self exclusion gaming apps blocking fail in the same handful of ways, and all of them are avoidable in the first fifteen minutes.
- Leaving a balance behind. Withdraw before you lock, or the exclusion becomes a waiting room with money in it.
- Doing one device. The tablet in the drawer and the old phone in the cupboard both have browsers.
- Blocking apps but not browsers. Nearly every app has a web version that opens in one tap.
- Holding your own passcode. A block you can lift in ten seconds will be lifted in ten seconds.
- Leaving notifications on. A single promotional push at the wrong hour undoes a fortnight of quiet.
- Choosing a short period to “test it”. Short periods test nothing except whether you can wait a week.
- Telling nobody. A break that someone else knows about is a great deal harder to quietly abandon.
- Treating it as the whole plan. Containment buys time; it does not by itself change what the playing was doing for you.
Add one more that is less obvious: do not set the whole thing up in the middle of a bad night. Decisions made in the hour after a heavy loss tend to be either too drastic to stick to or too vague to matter. Set it up on an ordinary afternoon, with the banking app open and your phone settings in front of you, and treat it as admin rather than as a reckoning.
And do not quietly keep a route open as insurance. One card left unrestricted, one browser left unblocked, one account left dormant rather than closed — these are usually chosen on purpose, with a story attached about why that one is different. It never is. If you notice yourself making an exception while you build the setup, that exception is the thing most likely to end it.
Where to get free, confidential help
If the pattern has moved past the point where a block fixes it — borrowed money, hidden spending, lost sleep, lying about it — the layers described here are still worth setting up, but they are not the thing that will help most. Talking to someone is, and it costs nothing.
Free mental-health helplines operate in India in multiple languages and will take a call about compulsive spending or app use without requiring a diagnosis or a label. Several non-profits also run free, confidential chat and forum support that is open regardless of where you are, and none of them ask for payment or account details. If anyone contacts you demanding a fee to release a payout, to lift a block, or to recover money you have lost, that is the pattern of a scam rather than a service, and the honest response is to stop replying rather than to pay.
Telling one person in your own life matters as much as any helpline. It does not have to be a confession or a long conversation — handing over a passcode and saying you are taking six months off is enough to turn a private decision into one with a witness, and that is most of what makes a break survive a dull Tuesday evening.
One short honesty line, because it belongs here rather than in a disclaimer at the bottom: these products are for adults only, real-money play carries real risk, and over any meaningful stretch of time losing is the expected outcome rather than the unlucky one. Nothing in a break setup changes that arithmetic — it only changes how much of your month is spent inside it.
Set the three layers, tell one person, write the date down, and give it six months rather than six days. That is the whole method, and it is unglamorous on purpose.
Frequently Asked Questions
What is self exclusion in online gaming?
It is a voluntary instruction you give in advance — to a platform, to your own device, or to your bank — that removes your ability to log in, install, or deposit for a set period. It is not a penalty and nothing is recorded publicly. In-app versions range from a short cooling-off window to a longer closure that cannot be lifted on request during the period.
How do I block gaming apps on my own phone?
Uninstall the apps, then use your phone’s built-in screen time or digital wellbeing controls to restrict the app category and turn on install restrictions, protected by a passcode you do not use elsewhere. Repeat the block in every browser on the device, clear saved logins, remove saved cards and autofill entries, switch off notifications, and give the passcode to someone you trust so lifting it requires a conversation. Then repeat the whole process on every other device you own.
Does self exclusion actually work?
The evidence generally points to reduced deposits and spend among people who use exclusion and limit tools, though the size of the effect varies a lot between studies and some activity simply moves elsewhere. Be wary of any single tidy percentage. What looks sturdiest is that longer periods hold better than short ones, combined tools beat any single tool, and telling another person improves the odds.
Can I ask my bank to block payments to gaming apps?
Often yes, and it is the strongest of the three layers because it works regardless of which app is used. Check your banking app’s card controls first, then ask about a merchant-category restriction, a reduced daily online transaction limit, disabling online card use, lower per-transaction payment limits, or cancelling card-on-file mandates. Availability varies by bank, and a loaded wallet or a second account is not covered by a card block.
What is a cooling-off period in gaming apps?
A short fixed freeze on your account, commonly 24 hours, 7 days, or 30 days. It usually cannot be cut short, and it ends automatically when the window closes without you having to choose to come back. That makes it a useful circuit breaker for a single bad night, but a weak tool for a real break, since the account reopens by itself. Withdraw your balance before triggering one.
Can I reverse self exclusion if I change my mind?
It depends on the layer. A cooling-off period simply lapses when its window ends. A longer exclusion generally cannot be lifted during the stated period, and reopening afterwards usually needs an explicit request plus a waiting period. Device blocks can be removed by whoever holds the passcode, and bank restrictions can usually be reversed on request, sometimes after a deliberate delay. If you are trying to reverse something within days of setting it, the delay is working as intended.
